Rapidious’ Q2 Market Data: Pressure on Used Class As, Movement in Other Segments
Rapidious, the real-time market intelligence platform built for the RV industry, released its Q2 2026 RV market findings, highlighting a market moving in two different directions at once: Class A used inventory is aging sharply, while travel trailers, pop-up campers and fifth wheels are showing signs of stronger movement.
The findings draw on Rapidious market intelligence across U.S. dealer lots, including segment-level inventory movement, regional velocity, model-level aging and pricing against market benchmarks.
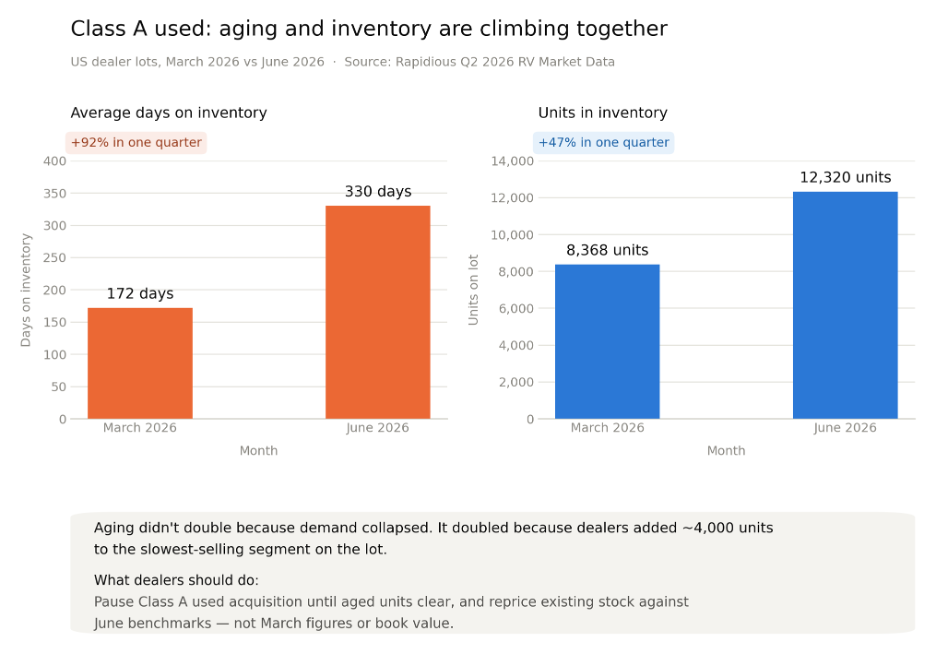
In the Class A used segment, average days on inventory rose from 172 days in March to 330 days in June, a 92% increase, while inventory grew from 8,368 to 12,320 units, a 47% increase.
“The headline is not simply that Class A used units are aging,” said Kishore Rajgopal, founder and CEO of Rapidious. “The real issue is that dealers are adding inventory into segments that are already moving slowly. In the second half of 2026, the winners will be dealers who manage inventory by live market signals — not by last quarter’s assumptions, national averages or static book values.”
Rapidious’ analysis suggests that Class A aging did not increase in isolation. The segment also absorbed roughly 4,000 additional units during the quarter, intensifying pressure in a category that was already slow-moving. For dealers, that makes Class A used acquisition a more selective decision heading into the second half of the year.
The data also shows significant regional variation in inventory velocity. In June, comparable inventory moved in 125 days in Maine and 150 days in Texas, while slower-moving states included South Dakota at 289 days, Alabama at 245 days, Ohio at 223 days, Wyoming at 220 days and Florida at 217 days.
“The national average can be misleading because it hides local reality,” Rajgopal added. “A dealer in a fast-moving market may be discounting too early, while a dealer in a slower market may be holding price too long. The same national number can create opposite mistakes in different states.”
While Class A used inventory showed pressure, other segments improved during Q2. Travel trailer used inventory improved from 182 to 152 days, while sold count rose from 11,948 to 14,441 units. Pop-up campers improved from 180 to 163 days, with sold count rising from 443 to 593 units. Fifth wheel used inventory held relatively steady at 176 days, while its pricing gap against benchmarks narrowed.
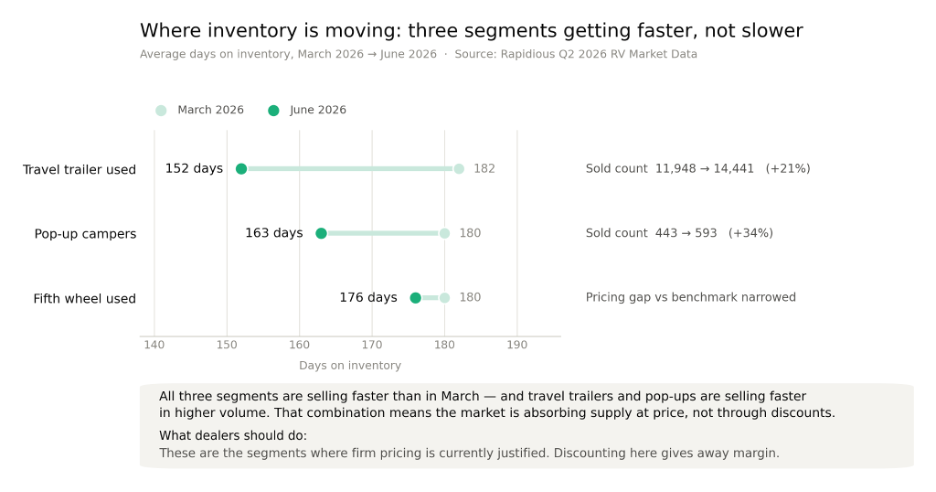
“These are the segments where inventory dollars appear to be working harder,” Rajgopal said. “For many dealers, the opportunity in H2 2026 is not simply to discount more. It is to understand where demand is actually holding, where pricing can remain firm, and where acquisition discipline needs to tighten.”
Based on the Q2 findings, Rapidious identified three priorities for dealers heading into the second half of 2026:
- Tighten Class A used acquisition. Reprice existing stock against current market benchmarks rather than March figures or static book values.
- Use local and state-level market signals, not just national averages. Regional velocity varies significantly, and national averages can hide local risk.
- Protect margin in improving segments. Travel trailers, pop-up campers, and fifth wheels are showing better relative movement, making blanket discounting less appropriate.
Rapidious will share additional Q2 and H2 2026 market insights with dealers at the RVDA Convention & Expo, taking place Nov. 9–13 at Paris Las Vegas. Rapidious will exhibit at booth #805, where dealers can benchmark their own inventory against live market intelligence.